From Listing Books to Artificial Intelligence
Every day, millions of Americans search for homes online.
They browse listings on their phones while waiting for coffee. They compare prices, property taxes, school information, commute times, neighborhood amenities, flood exposure, satellite images, and sales histories. They save favorite properties, create alerts, and scroll through homes in cities they may never have visited.
To the consumer, the process feels almost effortless.
A home is listed. It appears online. Buyers find it. The property sells.
Most people never stop to ask where the information came from, who organized it, or why the American real estate industry still depends on hundreds of local and regional listing networks to produce what looks, from the outside, like one national search experience.
Hidden beneath nearly every major property portal is one of the oldest surviving information-sharing systems in American business: the multiple listing service, better known as the MLS.
The MLS was not created for the internet. It was not created for smartphones, cloud computing, consumer portals, virtual tours, or artificial intelligence. It emerged in a world of paper records, personal relationships, local exchanges, and extraordinarily scarce information.
Its earliest purpose was not to give the public a search engine. It was to help competing brokers cooperate. The property information was essential, but the economic engine was the opportunity to complete more transactions by sharing inventory and working with other brokers.
That model was ingenious for its time. It turned isolated collections of private information into cooperative marketplaces. It helped sellers reach more buyers, helped buyers discover more inventory, and created order in a business that had little standardization.
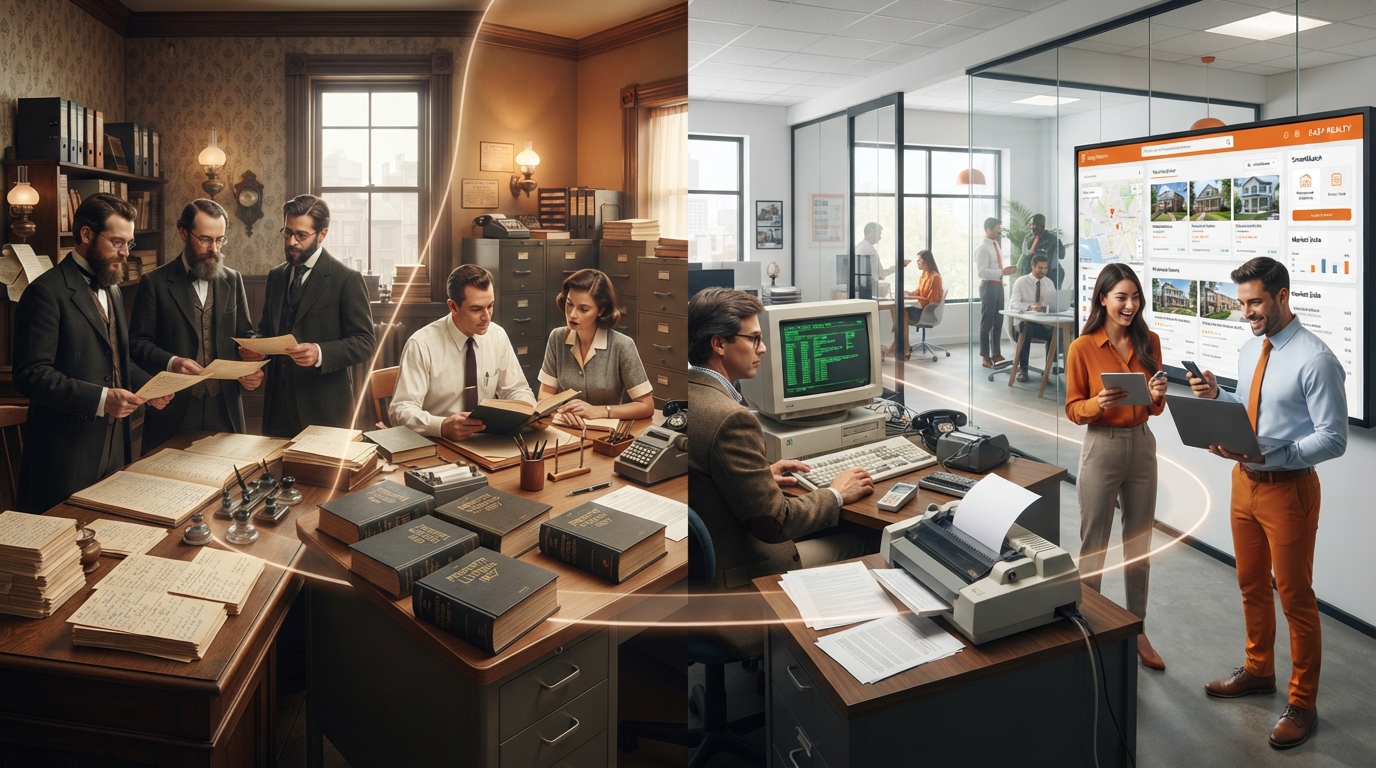
But a structure designed for local markets in the age of paper did not disappear when the paper did. The listings moved into books, then terminals, then databases, then websites, while many of the local boundaries, governance systems, participation rules, and economic interests survived.
That is what makes the history of MLS so interesting. It is not a simple story of progress from primitive books to modern technology. It is the story of an extraordinarily successful information system that repeatedly adopted new tools while preserving much of the institutional architecture built around the old ones.
For readers who want the concise explanation before exploring the complete history, our guide to what an MLS is and how it works explains the modern system, its participants, and its role in the real estate business.
To understand why the United States still has roughly five hundred MLS organizations rather than fifty statewide systems or one connected national framework, we have to go back to the beginning.
Before the MLS: A World of Information Scarcity
Imagine working as a real estate broker in the late nineteenth century.
There is no internet, no electronic database, no online public record, no digital map, and no central source of available properties. Information travels through newspapers, letters, printed circulars, telephone calls where service exists, and, most importantly, personal relationships.
If your brokerage has ten properties for sale, you know about those ten properties. A competing broker across town may have the perfect house for your client, but you might never learn that it exists. Another broker may represent a buyer who would gladly purchase one of your listings, but the buyer may never see it.
The market’s problem is not a lack of willing buyers or willing sellers. The problem is visibility.
Every brokerage is effectively its own island. Each broker controls a private inventory and a network of contacts. Information itself is a competitive asset, and preserving that advantage can appear more valuable than sharing it.
Yet hoarding information carries a cost. A listing that remains secret from most of the market reaches fewer possible buyers. A buyer whose broker knows only a narrow slice of available inventory sees fewer choices. Transactions that could benefit everybody fail to happen because the parties never find one another.
According to the National Association of REALTORS’ historical account, multiple listing in one form or another dates to the nineteenth century. Members of early real estate exchanges met on appointed days to trade information about listings. Some arrived prepared to purchase property needed by their clients but listed by another broker. The term “multiple listing” was in use by at least 1907, and the practice became widely accepted during the 1920s.
That history matters because the MLS was not invented in a single moment. It evolved from repeated experiments in cooperation.
The first breakthrough was not software. It was a change in thinking: competitors recognized that carefully structured cooperation could create more value than isolation.
The First Listing Exchanges
The earliest listing exchanges would not look like an MLS to a modern agent.
There was no search bar and no photo carousel. Brokers gathered in rooms, spoke about available properties, wrote information on blackboards or cards, and distributed updates by hand.
Historical accounts trace multiple-listing practices to real estate exchanges operating during the 1880s and 1890s. These exchanges created organized opportunities for brokers to share the properties they had available and identify properties needed by their clients.
The details sound quaint now, but the idea was radical.
Real estate professionals were attempting to create a living market of shared information when the available technology consisted of paper, ink, couriers, and conversation.
The exchange also solved a trust problem. In that era, professional licensing and regulation were far less developed than they are today. An organized board gave brokers a circle of participants whose commitments could be governed by shared expectations. The information had value because participants had some reason to trust its source and some process for cooperating when a buyer and a listing came together.
The resulting system was both cooperative and competitive.
Brokers still competed for clients, listings, reputation, and income. But they cooperated on the movement of inventory through the market.
The bargain was straightforward:
Help me sell my inventory, and I will help you sell yours.
1908 and the Rise of Organized Real Estate
In 1908, the organization now known as the National Association of REALTORS was founded in Chicago as the National Association of Real Estate Exchanges.
It began with 120 members, nineteen local boards, and one state association. Its stated aim was to unite real estate professionals and exert a combined influence on matters affecting real estate interests.
The national organization did not create the first listing exchange. Local cooperation already existed. What it helped create was a broader institutional framework in which standards, ethics, and organized professional practices could spread.
The association adopted its Code of Ethics in 1913. In 1916, it changed its name to the National Association of Real Estate Boards, and the term REALTOR was devised to identify members of the national association. The organization took its present name, the National Association of REALTORS, in 1972.
That distinction still matters.
A real estate license is issued by a state.
REALTOR membership identifies participation in a private trade association.
An MLS is a professional marketplace and information system.
These concepts became deeply connected in many markets, but they are not the same thing.
The distinction has produced decades of confusion among agents and consumers. Our article explaining why REALTOR is not a real estate license or job title explores that difference in greater detail.
As real estate boards became more formal, multiple-listing activity became more structured. Informal cooperation developed into governed cooperation. Listing forms, submission requirements, professional obligations, dispute processes, and participation standards created a level of order that personal relationships alone could not provide in a growing market.
The Economic Engine: Cooperation and Compensation
Today, many people think of an MLS as a property database.
Historically, that description is incomplete.
The database is the container. The original engine was cooperation among brokers.
Why would a broker share a valuable listing with competitors?
Because another broker might bring the buyer. A completed transaction could produce compensation for the professionals involved while accomplishing the seller’s objective.
This structure aligned incentives.
The seller’s property reached more potential buyers. Buyers represented by other brokers gained access to more inventory. The listing broker expanded the marketing reach of the listing, and another broker had a reason to devote time to finding a match.
For generations, offers of cooperative compensation became embedded in MLS practice. That history is essential to understanding both the success of the MLS and the intensity of later debates over compensation.
The seller usually had the sale proceeds from which the transaction’s commissions could be paid at closing. The buyer, meanwhile, was already assembling a down payment, closing costs, reserves, and moving expenses. Routing compensation through the listing side became a way to finance cooperation from the transaction proceeds rather than requiring the buyer to produce an additional professional fee in cash.
But the arrangement also created the tension that still troubles many sellers:
The seller could effectively fund the professional whose duty was to help the buyer negotiate, investigate, and decide whether to proceed.
From the seller’s perspective, it can feel like paying someone to argue the other side of the transaction.
That tension does not erase the historical logic. It reveals that a solution designed to make buyer representation financially accessible also distributed its cost in a way that could appear contradictory.
The phrase “commissions are negotiable” is frequently repeated without explaining what is actually being negotiated, who pays whom, and how compensation flows through the brokerage. Our guide to what negotiable real estate commissions really means examines the subject from that practical perspective.
The rules have since changed. The National Association of REALTORS’ 2024 practice changes removed offers of compensation from MLS displays and required written buyer agreements in many circumstances before touring homes.
Those changes do not erase the MLS’s cooperative history. They mark another stage in its evolution. For additional context, see our article on the NAR lawsuit aftermath and its effect on brokerage practices.
When the MLS Became Infrastructure
By the 1920s, according to NAR’s historical summary, multiple listing had become widely accepted. What began as an exchange among brokers was becoming market infrastructure.
That transformation happened gradually.
More brokers joined.
More listings entered the system.
The system became more useful.
As usefulness increased, participation became more attractive.
Today, technology companies call that a network effect. The value of a network increases as more people and more information enter it.
The MLS demonstrated that effect long before the term became fashionable.
A listing marketplace with ten participants was useful. One with hundreds could become indispensable. Once an MLS contained the most comprehensive professional inventory in a market, a broker outside it risked seeing less inventory and offering less exposure.
The MLS did more than aggregate listings. It aggregated confidence, rules, professional conduct, historical information, and the promise that other participants would work within a common framework.
Infrastructure becomes powerful when people build their routines around it.
Agents learned to begin their searches there. Brokers built listing procedures around it. Associations developed governance around it. Vendors designed products for it. Consumers eventually encountered its data through other websites without realizing that the MLS stood underneath the experience.
The Printed Listing Book
For much of the twentieth century, the MLS was a book.
Listings were compiled onto cards and pages, then distributed through printed volumes. Depending on the market and period, updates could arrive weekly, twice monthly, or on another schedule. Agents visited association or brokerage offices, obtained the newest material, and searched manually.
A modern agent may find the process painfully slow.
A property could be sold, withdrawn, or repriced before the next book reached every user. Photographs were limited. Corrections were cumbersome. Searching meant turning pages, reading descriptions, and marking possibilities by hand.
Yet the printed MLS book was revolutionary because it centralized information that had once been scattered across competing offices.
The book was the search engine of its day.
Its significance was not speed. It was access.
For the first time, an agent could sit at a desk and survey a broad professional inventory without calling every competitor in town. Sellers obtained exposure beyond one office. Buyers saw more possibilities. Brokers could cooperate at scale.
The books also reinforced the local shape of the MLS.
Printing and delivering a local volume was practical. Producing and continuously updating a statewide or national book was not. Local boards already had offices, members, geography, and governance. The physical medium itself favored a local institution.
This is one reason MLS fragmentation was rational.
The system developed around the limits of paper.
The Great Expansion of American Housing
The growth of the MLS cannot be separated from the growth of American homeownership after World War II.
The country emerged from the war with pent-up housing demand. Millions of service members returned to civilian life. Young families formed. Construction methods became more standardized, and large suburban developments expanded outside major cities.
The Servicemen’s Readjustment Act of 1944, better known as the GI Bill, included support for veterans seeking to purchase homes, farms, or businesses.
New Deal-era mortgage institutions and federal insurance programs had already helped move the mortgage market away from short loans with large balloon payments toward longer-term amortized financing. In the postwar period, those systems combined with rising wages, mass construction, highway expansion, and strong demand to reshape where and how Americans lived.
Levittown became the most famous symbol of this new suburban scale. Builders applied assembly-line methods to housing construction, dividing work into repeatable tasks and producing entire neighborhoods rather than individual houses one at a time.
The boom created an enormous information challenge for real estate professionals.
A small market with a limited number of homes could operate through personal knowledge and informal conversation. A metropolitan region spreading across newly developed suburbs could not.
Every subdivision created more inventory.
Every resale created more history.
Every expansion of the commuting area enlarged the geography relevant to buyers.
The MLS was perfectly positioned to absorb that complexity.
More listings made the system more valuable. More transactions generated more comparable sales. More geographic reach made cooperation more important. As housing developed at scale, listing information also had to be organized at scale.
This growth was not equally available to everyone.
Federal housing policy, mortgage underwriting, restrictive covenants, discrimination by private institutions, and exclusionary practices by some real estate boards helped deny many Black families and other minorities the same access to suburban ownership and professional networks.
Access to local real estate boards often determined access to the local MLS. Exclusion from the board could therefore mean exclusion from the central professional marketplace.
The history of the Thompson Broker model grew from the efforts of brokers who challenged those structures. Our article on the history of the Thompson Broker introduces that history, while The Realtor Associations’ Dark Past examines the broader legacy of exclusion within organized real estate.
That history belongs in the story because information systems are never purely technical.
Rules about who may participate shape who may compete, whose clients gain access, and who benefits from the network.
The postwar MLS therefore carried two legacies at once. It helped make a rapidly expanding housing market more efficient, but the institutions controlling access did not always serve everyone equally.
Standardization: The Quiet Revolution
The visible product of the MLS was the listing.
One of its most important achievements was the standardized structure beneath the listing.
Consider a market in which every broker records information differently.
One measures living area one way. Another measures it differently. A third provides no measurement at all. Property types, statuses, features, room counts, and remarks vary from office to office.
Comparisons become difficult and errors multiply.
MLS organizations imposed order.
Standard forms and required fields made information easier to compare. Status definitions clarified whether a property was active, pending, closed, withdrawn, or expired. Rules governed when changes had to be reported. Historical records accumulated.
This standardization did not eliminate differences among local MLSs. In fact, independent local definitions later became one of the barriers to combining data.
But within each market, the structured fields made the information far more useful than a stack of advertisements.
The MLS was turning descriptions into data before most businesses spoke in those terms.
That transformation prepared the industry for computerization.
A computer cannot readily search a pile of inconsistent narratives. It can search fields, categories, prices, dates, and statuses.
The work of standardizing listing information made digital search possible.
Computerized MLS Systems
The transition from books to computers did not happen in one national moment.
Different markets adopted different systems, hardware, and timelines. Some agents first encountered MLS data through office terminals and proprietary networks. Others moved through dial-up services, desktop software, and eventually web browsers.
Whatever the local path, the change was profound.
A book is a snapshot. A database can be updated.
A book must be searched with human eyes. A database can filter.
A book occupies shelves. A database can preserve years of listing history and generate market statistics.
Computerization accelerated the real estate market because information moved faster. New listings could become visible sooner. Price changes and status updates could reach participants more quickly. Searches that once consumed hours could be completed in minutes.
It also expanded the product.
MLS information was no longer limited to a current inventory. Digital systems could preserve prior listings, sales data, days on market, price changes, property characteristics, agent records, and market trends.
Data itself became an asset.
Yet the structural change was less dramatic than the technological one.
The local listing book became a local database.
The participating association remained.
The jurisdiction remained.
The membership and fee systems remained.
The computer removed many physical limits on sharing, but it did not automatically remove the institutions built around those limits.
That is a central theme in the evolution of the MLS:
The technology changed faster than the boundaries.
Why Local Boundaries Survived Digitization
It is tempting to assume that once computers arrived, every local MLS should have merged into a much larger system.
But technology was only one part of the equation.
Local MLSs had owners, boards, staff, rules, budgets, contracts, vendors, and members. They reflected local practices and political relationships.
Data fields differed.
Participation agreements differed.
Lockbox systems differed.
Merging MLS systems meant reconciling not only databases but institutions.
Local knowledge also had legitimate value. Real estate remains tied to place. Markets differ in property types, customs, geography, regulation, and terminology.
A coastal condominium market does not operate exactly like a rural land market or a dense urban cooperative market.
For many participants, local control was not an outdated inconvenience. It was the reason the system responded to local needs.
The strongest argument for consolidation was therefore not that local expertise had no value.
It was that local governance and broad data access did not necessarily have to be mutually exclusive.
That distinction opened the door to regional systems, reciprocal access, data shares, common technology vendors, and MLS standardization efforts.
The Rise of Regional MLS Systems
The history of MLS is a story of fragmentation, but it is also a story of consolidation.
As technology improved and metropolitan economies spread across county lines, neighboring markets found growing value in larger information networks.
Agents working in one city increasingly served clients in surrounding counties. Buyers did not stop their searches at association boundaries. Brokers operating across multiple markets faced duplicate fees, logins, training, rules, and data feeds.
Regional MLS organizations offered a practical answer.
Some local systems merged outright.
Others created reciprocal-access agreements.
Multiple associations sometimes became shareholders or customers of a common MLS company.
Data-sharing arrangements allowed users to see neighboring inventories without joining every organization separately. Technology costs could be spread across a larger subscriber base.
Stellar MLS is a strong Florida example. Its published shareholder and customer list shows numerous REALTOR associations participating in one regional MLS organization, and it promotes reciprocal access and integrated data shares with other systems.
The significance is larger than one company.
Regionalization proves that the industry’s geography is not fixed. Boundaries can change when enough participants believe a broader network creates greater value.
But regionalization can also create extremely large organizations that remain separate from other extremely large organizations.
Consolidation reduces the number of systems without necessarily producing statewide access.
This is why counting MLSs can be surprisingly difficult.
Organizations merge, rename, share platforms, participate in data exchanges, or maintain separate governance while integrating some inventory.
The Easy Life Journal has previously examined the question in Why Are There 489 MLS Systems in the United States? and the Florida-focused article If MLS Doesn’t Control Commissions Anymore, Why Do We Still Have 30 of Them in Florida?.
Those earlier articles address the issue directly. This article goes further by placing that fragmentation inside the complete history of the MLS.
The exact national count continues to change as organizations consolidate and as industry sources apply different definitions.
The larger reality is clear:
The United States still relies on hundreds of separately governed listing marketplaces to create a consumer experience that increasingly appears national.
The Internet Revolution
If computers changed how real estate professionals managed information, the internet changed who could see it.
Before online search, the consumer’s path usually began with a professional.
A buyer told an agent what they wanted. The agent searched the MLS, selected possibilities, and presented them.
The internet allowed consumers to begin by themselves.
They could browse listings at night, compare unfamiliar cities before relocating, watch price changes, and arrive at the first conversation with an agent already knowledgeable about the available inventory.
This was more than a new advertising channel.
It shifted the balance of information.
Consumers no longer accepted scarcity as normal.
In travel, finance, retail, employment, and media, the internet made large bodies of information directly searchable. Property information became part of the same expectation.
The MLS remained essential because its structured data powered much of the experience. But the consumer often encountered that data somewhere else: on a brokerage website, an IDX search page, or a national property portal.
The source and the destination separated.
Realtor.com and the National Search Experience
Realtor.com illustrates both the power and the complexity of the portal era.
The name naturally leads many consumers to assume that the website is operated by the National Association of REALTORS.
It is not.
Realtor.com is operated by Move, Inc., a News Corp subsidiary. The REALTOR name is used through an arrangement with NAR, but the website itself is not owned and operated by NAR.
The distinction is important because the website’s brand connects it to organized real estate, while its operation belongs to a media and technology company.
The Easy Life Journal article Who Really Owns Realtor.com? addresses this exact misconception.
More important for the MLS story is what Realtor.com represented:
A broad consumer search experience built on listing information originating in many local and regional systems.
Consumers did not need to understand the boundaries beneath the screen. They searched by city, state, ZIP code, price, property type, and property features.
The portal made fragmented infrastructure feel unified.
Zillow, Redfin, Homes.com, brokerage websites, and other platforms reinforced the same consumer expectation.
The buyer did not ask which MLS governed a home.
The buyer asked whether the home was available and whether it matched the search.
The industry saw feeds, display rules, licenses, attribution, and compliance.
The consumer saw houses.
Data Syndication and the New Economics of Attention
The internet also altered the economics of listing exposure.
A listing entered into an MLS could flow outward through brokerage websites and portals. Wider distribution served the seller’s objective of reaching buyers, but it also created businesses built on capturing consumer attention around other people’s listings.
A portal could display a listing, attract a buyer, and sell advertising or leads to real estate professionals.
The listing agent might provide the underlying inventory while competing for visibility next to the listing.
That model explains why debates about portals are rarely just about data accuracy.
They are also about branding, lead ownership, consumer relationships, and who captures the economic value created by the listing.
The MLS solved one problem by sharing information.
The portal era created another:
Once information is broadly shared, who controls the experience around it?
The debate over listing distribution has also appeared in disputes over clear cooperation and private listings. Related Easy Life Journal coverage includes Zillow’s position on the Clear Cooperation Policy and the later Clear Cooperation Policy drama.
Florida as a Case Study in MLS Fragmentation
Florida makes the national structure unusually easy to see.
A Florida real estate license is statewide.
A sales associate or broker is not licensed only for Orlando, Tampa, Palm Beach, Naples, or Jacksonville. The legal authority comes from the state.
Consumer behavior is increasingly statewide as well.
Retirees compare Atlantic and Gulf Coast communities.
Investors evaluate rentals across several metropolitan areas.
Families relocate from South Florida to Central or North Florida.
Agents build referral and transaction businesses that cross local boundaries.
The listing infrastructure, however, developed regionally.
That was historically sensible.
Florida is large, and its markets evolved differently. Miami’s international condominium market, Orlando’s tourism and new construction, Tampa Bay’s regional economy, the Gulf Coast’s second-home demand, the Panhandle, and rural inland communities did not require identical local institutions.
Printed MLS books and early computer networks also made statewide, real-time coordination impractical. Local and regional organizations solved the problem with the tools available.
Today, a brokerage operating across Florida may participate in several MLSs to cover the markets its agents serve.
Easy Realty, for example, currently subscribes to Stellar MLS, BeachesMLS, and Southwest Florida MLS. That combination provides broad coverage, but it does not place every Florida listing under one governance system or one subscription.
The mismatch raises a straightforward question:
If the professional license is issued statewide, why should the professional listing search require a patchwork of regional access arrangements?
Local MLS leaders can answer that local governance protects market-specific needs, maintains relationships, enforces standards, and funds services used by participants.
Those are serious considerations.
The statewide argument is equally serious.
One system could reduce duplicate costs, training, logins, rules, data licenses, and administrative work. It could give every Florida licensee the possibility of searching the same statewide professional inventory, subject to participation rules, while preserving local expertise through regional governance or advisory structures.
My State MLS and similar organizations arise from this idea: the logical search area can follow the state license rather than the local association boundary.
The strongest version of the argument is not that every local MLS adds no value.
It is that modern technology makes it unnecessary to equate local value with isolated access.
A statewide MLS could still use regional fields, rules, compliance staff, market experts, data-quality teams, and local advisory groups.
The question is whether those functions require separate databases and separate participation relationships.
Florida has already demonstrated that consolidation is possible.
Stellar MLS serves numerous associations across a broad territory. BeachesMLS provides extensive South Florida coverage. Other large systems serve other regions.
The state is not divided into hundreds of tiny books anymore. It has moved toward fewer, larger networks.
But “fewer” and “one” are different destinations.
If Florida were designing its professional property-information system from scratch today, with statewide licensing, cloud infrastructure, real-time data exchange, and consumers already searching the whole state online, would it choose the same boundaries?
That is not an accusation.
It is the central thought experiment of the article.
MLS Access, Association Membership, and Agent Choice
The fragmentation debate also intersects with a related question:
Must access to property information remain bundled with local board, state association, or national trade-association membership?
For years, many agents assumed these relationships were inseparable.
They came to believe that obtaining or keeping MLS access automatically required them to maintain REALTOR association membership.
The relationship is more complicated.
A state license, brokerage affiliation, MLS participation, local association membership, state association membership, and NAR membership can represent different legal or contractual relationships.
Agents researching those distinctions may find these guides useful:
- How MLS access works without association membership
- How to get MLS access without joining the Realtor association in Florida
- Can you cancel NAR and keep your MLS access?
- Do real estate agents need MLS membership?
- What does MLS optional mean?
Easy Realty’s model separates brokerage affiliation from mandatory MLS participation.
For some agents, particularly those regularly serving our buyers and our sellers in MLS-dependent markets, direct MLS access remains an important business tool.
Other agents may build businesses around referrals, investors, new construction, rentals, direct relationships, or transactions that do not require continuing access to a local MLS.
The point is not that nobody needs MLS access.
The point is that not everybody needs the same access, memberships, and recurring costs.
That distinction is explored further in Florida Real Estate Brokerage Where MLS Is Optional and MLS Optional Versus MLS Required Brokerages.
Why the Fragmentation Persists
The spreadsheet analogy helps clarify the issue.
Imagine that every active Florida listing must appear in a professional spreadsheet.
The technology exists to create one statewide spreadsheet.
Instead, history produced a series of large regional spreadsheets, each with its own ownership, rules, subscription relationship, fields, and business interests.
Some spreadsheets share rows.
Some systems provide reciprocal access.
Portals ingest information from many of them and show consumers what appears to be one seamless statewide search.
From the outside, the fragmentation almost disappears.
From the brokerage side, it remains real.
Different applications, fees, policies, compliance obligations, data agreements, training requirements, and market boundaries create operational work.
The persistence is not proof that the system is irrational.
Institutions protect investments and priorities. Members may fear losing influence in a larger organization. Staff and leadership roles overlap. Technology contracts differ. Data harmonization is difficult. Local participants may distrust decision-making that feels geographically distant.
But these are governance and economic barriers, not limits of computing.
The paper book required local distribution. The cloud does not.
From Search Engines to Answer Engines
The internet transformed access to property information.
Artificial intelligence may transform interpretation.
Traditional online real estate search asks the consumer to translate life into filters:
- City
- Price
- Bedrooms
- Bathrooms
- Square footage
- Property type
- Selected features
Human needs are rarely so tidy.
A buyer may want a house where a boat can be kept legally, an aging parent can live privately, an airport is reasonably close, flood risk is manageable, a home office is quiet, and the monthly carrying cost stays below a particular limit.
That is not merely a filter set.
It is a collection of priorities, tradeoffs, and questions.
An AI-powered property search can begin with natural language, ask follow-up questions, combine listing fields with other authorized information, explain why a property may fit, and identify uncertainty that requires professional verification.
The consumer’s question changes from:
Which boxes should I check?
to:
Which homes solve my problem?
This shift makes the underlying database less visible.
A person asking an AI assistant to evaluate homes across Florida may never know which MLS originated each listing.
The value appears in the answer, not the source architecture.
The Easy Life Journal has already examined early examples of this transition in ChatGPT Introduces Zillow Search Feature and Are Realtors Becoming Obsolete Due to AI?.
That does not make data governance less important.
It makes data governance more important.
AI systems need accurate status information, consistent fields, reliable updates, clear licensing, and responsible treatment of uncertain or regulated information. Poor data can produce confident but wrong answers.
The MLS may therefore remain essential even if consumers interact with it less directly.
The system’s future role may be less about presenting search forms and more about providing trustworthy, structured information to a new generation of interfaces.
If We Were Inventing the MLS Today
Imagine that the MLS never existed.
There were no nineteenth-century broker exchanges, no printed books, no separate local databases, no inherited association boundaries, and no century of contracts and governance.
Now place brokers, agents, consumers, engineers, data scientists, regulators, appraisers, lenders, investors, and fair-housing experts in a room in 2026.
Give them a blank sheet of paper and one assignment:
Design the ideal professional property-information system for the United States.
Would they create one national database?
Fifty statewide networks?
Large regional systems?
A connected federation in which data is shared nationally but governance remains local?
There is no obvious answer.
A national system could provide scale and uniformity but risk becoming remote, rigid, or monopolistic.
Statewide systems align naturally with professional licensing but still must accommodate different local markets.
Regional systems can remain responsive but preserve boundaries that agents and consumers routinely cross.
The useful question is not which single model is perfect.
It is which parts of the current model exist because modern real estate requires them, and which parts exist because history handed them to us.
A system designed today would almost certainly start with interoperability.
Data would follow common standards. A broker operating across markets would not submit the same application, build the same feed, or learn the same workflow repeatedly. Authorized updates would move in real time. Consumers would be able to see where information came from and when it was last verified.
The system would need to serve professionals as more than a public portal.
Agents need listing input, history, showing tools, comparable sales, cooperation workflows, compliance rules, and accountability.
Brokers need control over their listings and data use.
Our sellers need accurate exposure.
Our buyers need reliable information and representation choices.
It would also need to acknowledge the lessons of the past.
Access rules can create exclusion.
Data fields can encode assumptions.
Automated recommendations can reproduce bias.
A modern MLS would require fair-housing safeguards, transparent governance, auditable decision-making, privacy controls, and meaningful paths for correction.
Most of all, a system designed today would recognize that the information problem has changed.
The founders of multiple listing lived in a world of scarcity.
They needed to find and distribute information.
We live in a world of abundance.
We need to authenticate, connect, interpret, and explain information.
That is why the future of MLS is not merely a faster database.
It is a more intelligent, interoperable, and accountable information network.
The Last Listing Book
At some point, somewhere in America, an agent opened the final printed MLS book they would ever use.
There was probably no ceremony.
No headline declared the end of the book era.
The agent simply completed a search, served a client, and later moved to the machine that made the book unnecessary.
That quiet transition captures the history of the MLS.
New tools did not arrive because the old system had been foolish.
They arrived because the old system had solved one generation’s problem well enough to reveal the next generation’s problem.
The early exchanges solved isolation through cooperation.
The printed book solved distribution.
Standardization turned descriptions into searchable data.
Computerization improved speed and history.
The internet opened the search to consumers.
Regional consolidation widened professional access.
Artificial intelligence may help people interpret abundance.
The MLS deserves enormous credit.
It helped transform disconnected local inventories into organized marketplaces. It created shared rules, expanded exposure for sellers, gave buyers access to more choices, and built an information foundation that now powers much of the public real estate internet.
But success should not make any institution immune from examination.
The question is not whether the MLS was valuable.
It was.
The question is whether a structure born from local meetings and printed books should remain fragmented in the same way when professionals are licensed by states, consumers search nationally, and technology can connect data instantly.
The likely future is not the disappearance of the MLS.
It is another evolution of the idea that created it:
Shared information becomes more valuable when people can use it efficiently.
The brokers who met in the nineteenth century could not have imagined a statewide cloud database.
The agents excited by a new listing book could not have imagined Realtor.com.
The architects of the first online searches could not have imagined an AI assistant discussing flood risk, carrying costs, commute priorities, and multigenerational living in one conversation.
Yet every one of those developments grew from the same fundamental mission:
Connect people with property information.
The tools changed.
The need endured.
The next chapter should not be constrained by the limits of the last one.